A high income can provide financial opportunities, but earning more money does not automatically mean you are wealthy. Someone who earns a large salary but spends nearly all of it may accumulate fewer assets than someone who earns less but consistently saves and invests.
This is why understanding net worth vs income is important when assessing your financial position.
Income measures the money you receive over a period of time. Net worth measures the value of your assets after subtracting your liabilities at a particular point in time.
Both measures matter, but they answer different questions. Income helps you understand your earning capacity and cash flow. Net worth shows what you have accumulated after accounting for what you owe.
Understanding net worth vs income is essential when evaluating your financial health. Income shows how much money you earn over a particular period, while net worth measures the wealth you have accumulated after subtracting your liabilities from your assets. Both figures matter, but they reveal different aspects of your financial position.
This guide explains the difference, shows how to calculate both, and outlines practical ways to improve your financial position.
What Is Income?
Income is money received from sources such as employment, business activity, investments, rental property, or other eligible sources.
Depending on the context, income may be reported before or after taxes and deductions.
Common forms include:
- Employment income: Salary, wages, bonuses, and eligible benefits.
- Business income: Earnings from a business or self-employment after relevant expenses.
- Investment income: Interest, dividends, and other investment distributions.
- Rental income: Money received from letting property, after considering relevant costs.
- Other income: Certain pension payments, royalties, and other receipts, depending on the individual’s circumstances.
For personal budgeting, take-home income is often particularly useful because it represents the money available after payroll deductions and taxes withheld.
Gross income is still important for employment comparisons, tax calculations, and some financial applications. Always make sure you compare like with like.
What Is Net Worth?
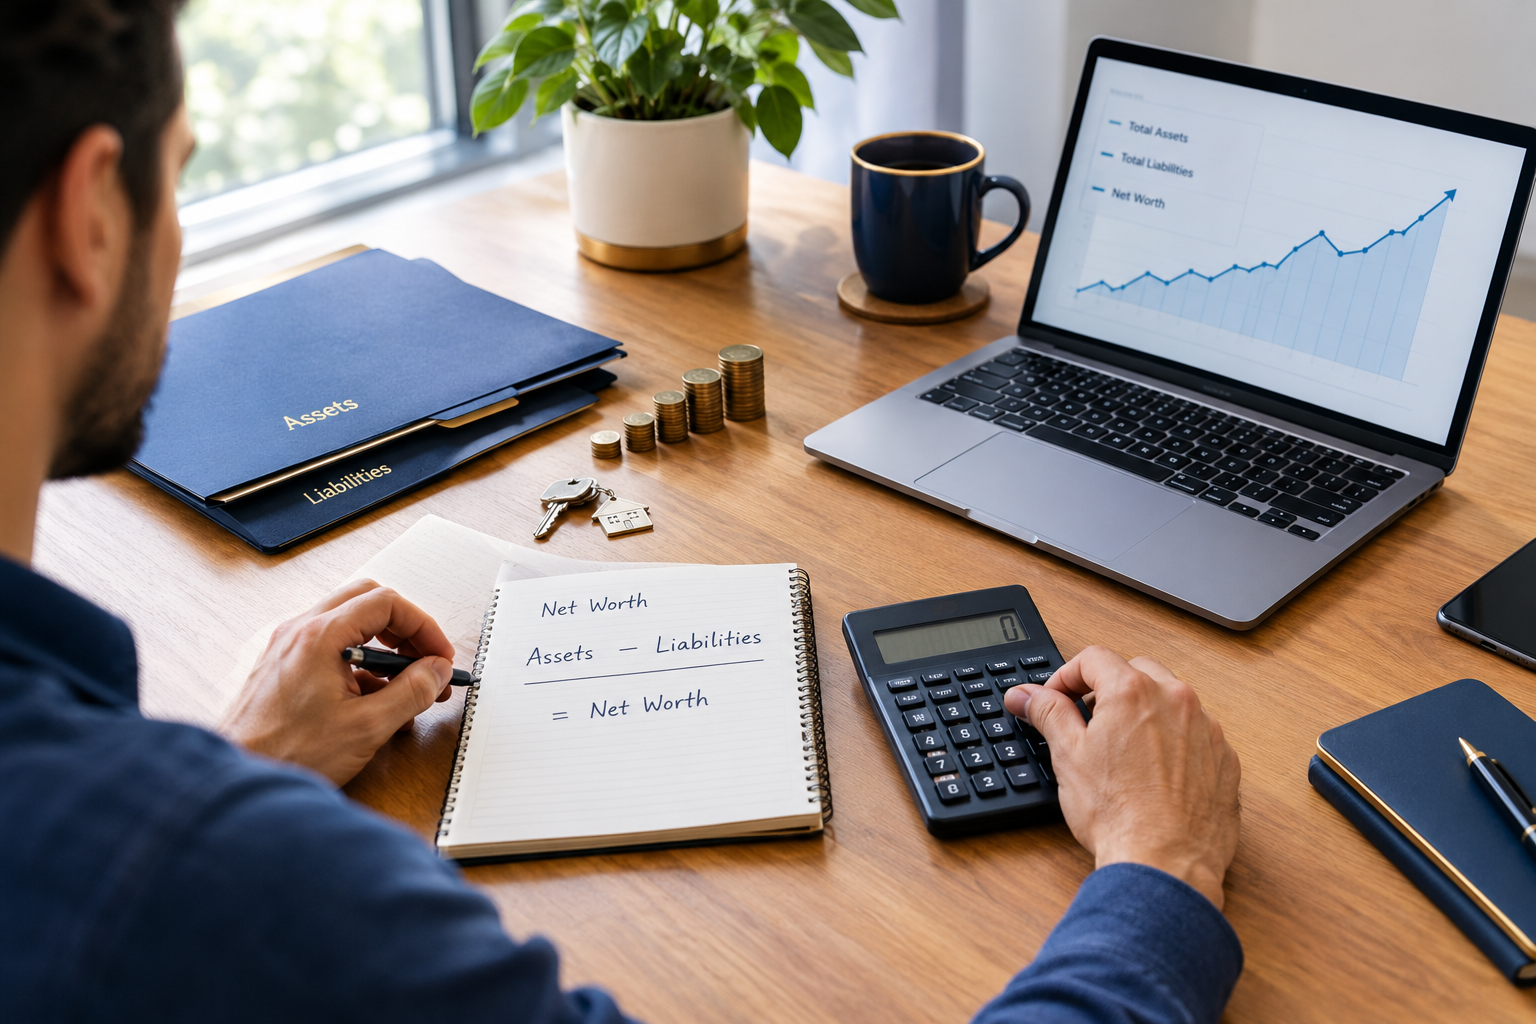
Net worth is the difference between the value of your assets and your liabilities.
Net worth = Total assets − Total liabilities
Assets are things of financial value that you own or have a recognised financial claim to. Liabilities are amounts you owe.
Examples of assets
- Cash and bank balances.
- Savings and investment accounts.
- Shares, bonds, and eligible fund holdings.
- Retirement savings and pension assets, where appropriate to the calculation.
- Property and other real estate.
- Business ownership interests.
- Other valuable assets that can be reasonably valued.
Examples of liabilities
- Outstanding mortgage balances.
- Credit card debt.
- Personal loans.
- Vehicle finance.
- Student loans.
- Other outstanding financial obligations.
When calculating net worth, use consistent valuation dates and reasonable estimates of current asset values. Avoid counting the same asset twice—for example, including both the full value of a portfolio and a separate account balance that is already included in that portfolio.
How to Calculate Your Net Worth
Suppose a person has the following assets and liabilities:
| Assets | Value |
|---|---|
| Cash and bank savings | 15,000 |
| Investment portfolio | 40,000 |
| Property value | 180,000 |
| Other assets | 5,000 |
| Total assets | 240,000 |
Their liabilities are:
| Liabilities | Outstanding amount |
|---|---|
| Mortgage | 120,000 |
| Vehicle loan | 8,000 |
| Credit card debt | 2,000 |
| Total liabilities | 130,000 |
Net worth is calculated as:
240,000 − 130,000 = 110,000
The person’s net worth is therefore 110,000 currency units.
This example illustrates an important point: the property is counted as an asset at its estimated value, while the outstanding mortgage is counted separately as a liability. The difference contributes to the person’s net worth.
The figures are illustrative and do not account for potential selling costs, taxes on asset disposal, or other adjustments that may be relevant in a detailed financial assessment.
Net Worth vs Income: The Main Differences
| Feature | Income | Net worth |
|---|---|---|
| What it measures | Money received over a period | Assets minus liabilities at a point in time |
| Time basis | Weekly, monthly, annually, or another period | A particular date |
| Main use | Budgeting, affordability, and cash-flow planning | Measuring accumulated financial position |
| Can it fluctuate? | Yes, with employment, business, or investment receipts | Yes, as assets and debts change in value |
| Does a high figure guarantee wealth? | No | Not necessarily; liquidity and future obligations matter |
| How to improve it | Increase earnings or other income sources | Grow assets, reduce liabilities, or both |
Income and net worth are related, but neither should be used as a substitute for the other.
A person may have a high income and low net worth because of spending, debt, or limited time to accumulate assets. Another person may have a modest current income but substantial investments and little debt accumulated over many years.
Why a High Income Does Not Always Mean High Wealth
A high salary can help someone save and invest, but what happens to that income matters.
Consider two individuals with the following monthly finances:
| Measure | Person A | Person B |
|---|---|---|
| Take-home income | 8,000 | 5,000 |
| Monthly expenses | 7,600 | 3,500 |
| Monthly surplus | 400 | 1,500 |
| Annual surplus before returns | 4,800 | 18,000 |
Person A earns considerably more, but Person B retains a larger portion of their income.
If these patterns continue, Person B may accumulate assets faster despite earning less. Actual net-worth growth will also depend on existing assets, debt repayments, investment returns, taxes, and unexpected expenses.
This is why salary alone is an incomplete measure of financial success.
Understanding your financial position requires looking beyond your monthly or annual earnings. Income measures the money you receive over a period, while net worth reflects the value of your accumulated assets after subtracting outstanding liabilities. Investor.gov explains how individuals can assess their financial situation by listing what they own and what they owe. Similarly, the Pew Research Center distinguishes income from wealth, highlighting why a high income does not necessarily mean someone has accumulated substantial wealth.
What Matters More: Net Worth or Income?
Neither is universally more important. Their importance depends on the question you are trying to answer.
Income matters when assessing cash flow
Income helps you determine whether you can meet monthly expenses, pay debt instalments, support dependants, and contribute to savings.
A person with substantial assets but very little accessible income may face cash-flow challenges. For example, wealth tied up in a property may not be readily available to pay everyday bills.
Net worth matters when assessing accumulated wealth
Net worth provides a broader picture of what you have built over time.
It can help you assess progress towards retirement, financial independence, major purchases, or other long-term goals. It also reveals the impact of debt that a salary figure alone cannot show.
However, net worth does not tell the whole story. A property-rich household may have high net worth but limited liquid savings. Someone with a large portfolio may also face substantial liabilities or future commitments.
Cash flow and net worth should be reviewed together
For a more complete picture, monitor:
- Monthly take-home income.
- Essential and discretionary expenses.
- Savings rate.
- Outstanding debt and repayment costs.
- Total assets and liabilities.
- Net-worth changes over time.
- Accessible emergency savings.
Together, these measures help you understand both your current financial capacity and your longer-term progress.
How to Increase Your Net Worth
1. Spend less than you earn
A sustainable gap between income and spending gives you money to save, invest, or repay debt.
This does not mean eliminating every discretionary expense. It means building a budget that supports essential needs, reasonable enjoyment, and your financial goals.
Equicio’s How to Create a Personal Budget guide can help you organise income and expenses.
2. Build an emergency fund
Unexpected expenses can force you to borrow money or sell investments at an inconvenient time.
An emergency reserve can help you manage disruptions to income and unplanned costs without undermining your wider financial plan.
See Equicio’s Emergency Fund guide for more information.
3. Manage expensive debt
Interest-bearing debt can absorb cash flow that could otherwise go towards savings and investments.
Review interest rates, fees, repayment schedules, and any early-repayment conditions. Paying down debt can improve net worth by reducing liabilities, although the best repayment strategy depends on the interest cost, liquidity needs, and any contractual considerations.
Equicio’s Debt Snowball vs Debt Avalanche article explains two common ways to organise debt repayment.
4. Invest consistently for appropriate long-term goals
Once immediate obligations and emergency reserves are addressed, investing may help you build assets over time.
The right investment approach depends on your time horizon, risk tolerance, local regulations, and financial circumstances. Diversified investments can still lose value, and returns are not guaranteed.
Avoid assuming that every investment will appreciate or that past performance predicts future results.
5. Increase your earning capacity
Professional development, new skills, career progression, business improvements, and carefully evaluated additional income sources may increase your earning capacity.
Higher income can accelerate wealth accumulation when part of the increase is saved or invested rather than fully absorbed by higher spending.
6. Review your net worth regularly
Calculate your net worth at a consistent interval—such as every three or six months—or annually if that suits your circumstances.
Record asset values, outstanding debts, and the date of each calculation. Use realistic valuations, particularly for property, private business interests, and assets that are not easily sold.
Look for trends rather than reacting to every short-term market movement. A decline in investment values does not necessarily mean your overall plan has failed, just as a temporary rise does not guarantee long-term success.
How to Track Your Net Worth Properly
A basic spreadsheet can be sufficient. List your assets in one section and liabilities in another, with a value and valuation date for each item.
For a useful comparison over time:
- Use the same valuation method where possible.
- Avoid double-counting assets or debts.
- Include outstanding loan balances, not just original loan amounts.
- Distinguish liquid assets from assets that are difficult to access.
- Track major changes such as property purchases, loan repayments, or new investments.
- Review changes in both total net worth and accessible savings.
If you use an investment or portfolio tracker, make sure that the portfolio values are current and that cash balances, deposits, withdrawals, and liabilities are handled consistently. Do not mistake transfers between your own accounts for new wealth.
Net worth can rise because you save more, repay debt, receive income, or experience asset-price appreciation. It can also fall because of spending, new borrowing, investment losses, or other changes. Understanding the cause of a change is more useful than looking at the headline figure alone.
Common Mistakes When Comparing Income and Net Worth
Comparing gross income with take-home income
One person’s reported income may be before tax while another’s is after tax. This can create misleading comparisons.
Ignoring debt
A person who owns expensive assets but also has large liabilities may have less net worth than the asset values suggest.
Counting illiquid assets as cash
A home or private business may contribute significantly to net worth but cannot necessarily be converted into spendable cash quickly or without costs.
Assuming a high net worth guarantees financial security
Financial security also depends on liquidity, the stability of income, the timing of expenses, insurance, and future obligations.
Focusing only on short-term changes
Investment values fluctuate. Use consistent measurements and consider the reasons behind changes instead of treating every movement as evidence of success or failure.
Frequently Asked Questions
What is the difference between net worth and income?
Income is the money you receive over a period, such as a month or year. Net worth is the value of your assets minus your liabilities on a particular date.
Can I have a high income but a low net worth?
Yes. High spending, substantial debt, limited savings, or a relatively short period of earning can leave someone with a low net worth despite a high income.
Is net worth the same as cash in the bank?
No. Net worth includes the value of eligible assets and subtracts liabilities. Assets may include investments, property, and other holdings that are not immediately available as cash.
How often should I calculate my net worth?
Quarterly, every six months, or annually can work, depending on your financial complexity and goals. The most important factors are consistency, realistic valuations, and using the information to make better decisions.
Can net worth be negative?
Yes. If total liabilities exceed total assets, net worth is negative. This can happen early in a career, during education, after a major purchase, or when debt is high. A negative figure is a starting point for planning, not a permanent judgment about future financial potential.
Should I focus on increasing income or reducing expenses?
Both can help. Increasing income can create more financial capacity, while controlling expenses allows more of that income to be saved or invested. The best approach depends on your current situation and the opportunities available to you.
Final Thoughts
Income determines how much money comes in; net worth shows what remains after accounting for what you own and owe.
A high income can create opportunities, but long-term wealth generally depends on what you do with the money you earn. Spending thoughtfully, managing debt, building reserves, investing appropriately, and tracking your assets and liabilities can all contribute to financial progress.
Rather than judging your financial position by salary alone, review income, spending, debt, liquidity, and net worth together. This provides a more useful foundation for planning major goals and measuring progress over time.
Ultimately, the comparison of net worth vs income provides a more complete picture of personal finances. A higher income can create opportunities to save and invest, but building net worth requires managing expenses, reducing debt and accumulating assets consistently over time.
Disclaimer: This article is for general educational purposes only and does not constitute personalised financial, investment, tax, or legal advice. Asset valuations, tax treatment, and the treatment of certain retirement or property assets can vary according to purpose and jurisdiction.