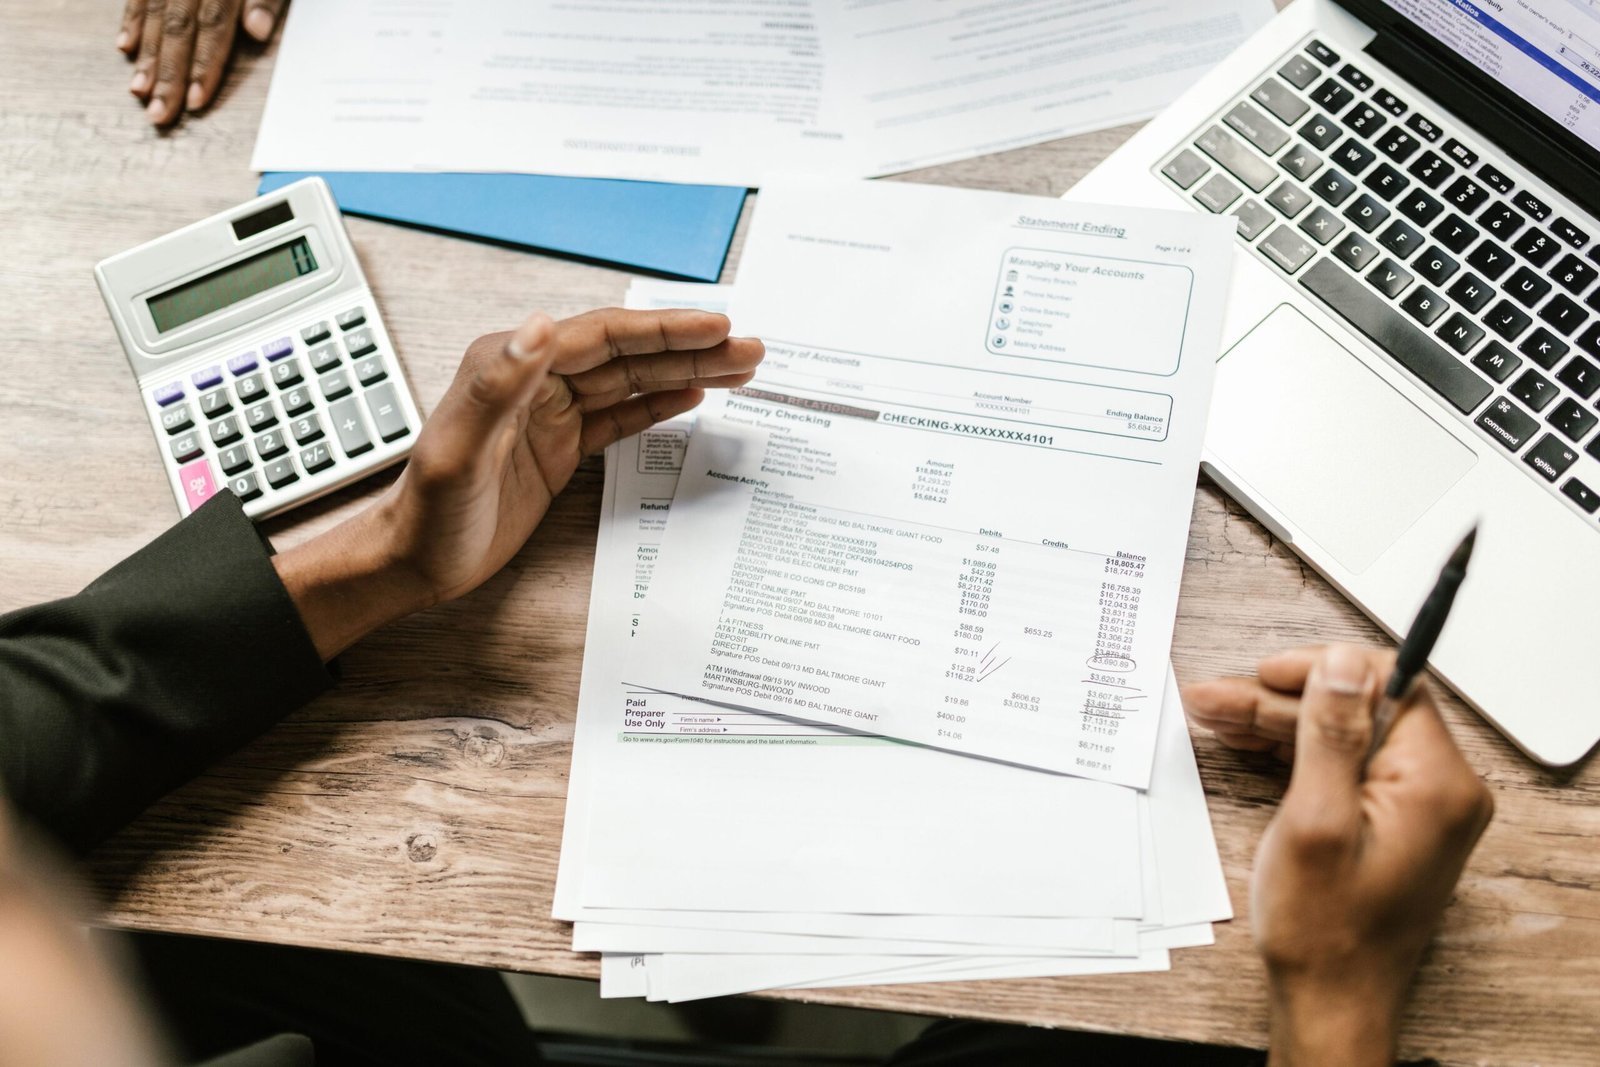
Financial profile banking is about how consistently your income, savings, borrowing and bank account activity reflect your actual financial circumstances. Banks may review these details when assessing applications, understanding transactions or carrying out customer due diligence. Maintaining accurate records and ensuring your financial activity is consistent with your circumstances can help you explain your finances clearly when questions arise.
Your financial profile is not created by one transaction, one payslip or one bank statement.
It develops over time.
Income, expenses, borrowing, savings, investments and account activity together create a picture of your financial behaviour.
This is why financial consistency matters.
Your Income Should Make Sense
If your declared income is Rs.300,000 per month, regular salary credits may create a straightforward pattern.
If significant additional amounts regularly enter the account, the bank may need to understand their source and purpose.
This does not mean additional income is wrong.
It means your financial records should accurately reflect your circumstances.
Your Borrowing Matters
A person earning Rs.300,000 with Rs.20,000 of monthly debt payments has a different financial position from someone earning the same amount with Rs.150,000 of monthly obligations.
Before taking additional debt, calculate your total repayment burden.
Use the [Loan EMI Calculator] and review your existing obligations.
Your Savings Matter
A growing savings balance can strengthen financial resilience.
But savings should also have a purpose.
Emergency savings, short-term goals and long-term investments should not necessarily be managed identically.
See [How Much Emergency Fund Should I Have?] and [How Much Money Should I Keep in Cash?].
Your Account Activity Should Reflect Reality
Do not move money between accounts simply to make your financial position look stronger.
Genuine financial activity creates a more meaningful record than temporary movements.
If you receive a large legitimate amount, keep reasonable evidence supporting the source.
Financial Profile Banking: Key Factors Banks Consider
Banks may consider several aspects of a customer’s financial circumstances when reviewing an account, assessing a financing application or conducting routine monitoring. These may include the customer’s occupation, expected income, source of funds, transaction patterns and declared purpose of the account. The checks required depend on the customer, product, risk assessment and applicable regulations.
A consistent financial profile helps make these details easier to understand. For example, salary credits that broadly match declared employment income may be straightforward to explain. However, unusual deposits or activity that differs significantly from the expected pattern may lead a bank to request supporting information.
Common Financial Profile Inconsistencies
Inconsistencies do not automatically indicate wrongdoing, but they can require clarification. Examples include frequent large cash deposits that are difficult to reconcile with declared income, transfers that have no clear explanation, or account activity that differs substantially from the stated purpose of the account.
Customers should keep relevant documents, such as salary slips, tax records, business invoices, sale agreements and evidence of transfers, where applicable. The appropriate documents depend on the nature and source of the funds.
How to Maintain a Consistent Financial Profile
Start by keeping your personal and employment information up to date with your bank. Use accounts appropriately, retain records of significant transactions and ensure that information provided to financial institutions is accurate. If you receive an unusual payment, keep evidence explaining its source and purpose.
If your income, occupation or financial circumstances change significantly, update the relevant information when required. Respond to legitimate bank requests promptly and provide accurate supporting documents. These practices can make your financial circumstances easier to explain, although they cannot guarantee approval of a banking or financing application.
Why Banks May Ask Questions
Customer due diligence requires banks to understand their customers and monitor account activity appropriately.
SBP’s current framework includes customer due diligence and ongoing monitoring within its AML/CFT/CPF supervisory approach.
A question from a bank is therefore not automatically a sign that something is wrong.
Practical Takeaway
A strong financial profile is built through:
Accurate information + sustainable borrowing + consistent savings + genuine transactions + good financial records.
Don’t try to create an artificial financial profile.
Build a genuine one.
For further information about banking regulations and customer due diligence in Pakistan, visit the official State Bank of Pakistan website.
Related Equicio Guides
- Source of Funds
- Bank Statement Analysis
- Banking Compliance
- What Makes a Bank Transaction Look Suspicious?
- Loan EMI Calculator
- Net Worth Calculator
Disclaimer
This article is general educational information and does not describe the internal assessment criteria of any particular bank.