Anti money laundering (AML) is the process of preventing and detecting the use of the financial system to disguise or move proceeds derived from criminal activity.
For banks and other financial institutions, anti-money laundering (AML) is not simply a compliance requirement. It is an important part of protecting the integrity of the financial system, understanding customer risk, detecting unusual activity and preventing financial services from being misused.
This guide explains the fundamentals of money laundering and AML from a practical banking perspective, with particular emphasis on customer due diligence, transaction monitoring, beneficial ownership, suspicious activity and internal controls.
Important: AML requirements vary by jurisdiction and institution. This article is intended for general knowledge and educational purposes and should not be treated as legal or regulatory advice.
What Is Anti Money Laundering (AML)?
Anti money laundering controls are designed to prevent, detect and respond to the misuse of financial institutions for money laundering and related financial crime.
The underlying criminal activity is often referred to as a predicate offence. Depending on the applicable legal framework, predicate offences can include fraud, corruption, bribery, theft, drug trafficking, illegal gambling, trafficking, counterfeiting and other serious crimes.
The purpose of AML controls is not to determine that every unusual transaction is criminal. Instead, financial institutions are expected to identify and assess risks, investigate activity where appropriate, and report suspicious activity through the channels required by applicable law.
A useful principle for bankers is:
An unusual transaction is an indicator for review, not proof of wrongdoing.
Why Does Anti Money Laundering Matter to Banks?
Banks sit at the centre of the financial system. Customers use accounts and financial services to receive income, make payments, transfer funds, invest, borrow and conduct business.
This makes financial institutions potentially attractive to individuals or organizations seeking to move or conceal illicit proceeds.
Effective AML controls therefore help institutions:
- Understand who their customers are
- Understand the purpose of customer relationships
- Identify beneficial owners
- Understand expected account activity
- Detect transactions that do not fit the customer’s profile
- Identify potentially suspicious patterns
- Meet regulatory and reporting obligations
- Protect the institution from financial, legal and reputational risks
Modern AML frameworks increasingly emphasize a risk-based approach. The current FATF Recommendations provide the international framework for combating money laundering, terrorist financing and proliferation financing, while allowing countries to adapt implementation to their own legal and financial systems.
The Commonly Described Stages of Money Laundering
Money laundering is commonly explained using three stages:
1. Placement
Placement refers to introducing proceeds of crime into the financial or economic system.
From a banking perspective, this may create an initial point at which unusual activity becomes visible.
2. Layering
Layering involves transactions or movements intended to make it more difficult to establish the origin or ownership of funds.
For financial institutions, complex or unusual transaction patterns may require closer examination when they are inconsistent with the customer’s known circumstances.
3. Integration
Integration refers to the point at which illicit proceeds appear to have become part of apparently legitimate economic activity.
The three-stage model is useful for understanding the concept, but real-world cases do not necessarily follow these stages in a neat or sequential manner.
Where Can Illicit Funds Enter the Financial System?
Potential exposure can exist across many financial products and services, including:
- Deposit accounts
- Cash transactions
- Fund transfers
- Remittances
- Investment products
- Securities and brokerage services
- Loans and financing
- Trade-related transactions
- Foreign exchange services
- Digital financial services
- Corporate and business accounts
- Correspondent banking relationships
- Payment services
The risk is not determined simply by the product itself. Customer type, geography, business activity, ownership structure, transaction behaviour and other risk factors also matter.
Anti Money Laundering, KYC and Customer Due Diligence
Know Your Customer (KYC) is one of the foundations of Anti Money Laundering (AML) controls.
KYC involves obtaining and verifying appropriate information about a customer and understanding the nature and purpose of the relationship.
Customer Due Diligence (CDD) generally involves areas such as:
- Identifying the customer
- Verifying the customer’s identity
- Understanding the purpose and intended nature of the relationship
- Identifying beneficial owners where applicable
- Understanding the customer’s business or source of income
- Assessing relevant risks
- Conducting ongoing monitoring appropriate to the risk
Customer onboarding should therefore be more than simply collecting documents.
The important question is:
Does the institution actually understand who the customer is, what the customer does, and what type of activity should reasonably be expected through the relationship?
For example, the State Bank of Pakistan’s Consolidated Customer Onboarding Framework brings together customer and account onboarding requirements for SBP-regulated entities, illustrating how KYC and customer due diligence form part of the formal onboarding process in a regulated banking environment.
Customer Identification Is Only the Beginning
A customer may provide valid identification documents and still present AML risk.
For example, a bank may know a customer’s name, address and identification details but have little understanding of:
- The customer’s actual business
- Expected turnover
- Sources of income
- Main suppliers and customers
- Ownership structure
- Expected transaction volumes
- International relationships
- The purpose of particular transactions
Effective AML controls therefore require an understanding of the economic purpose and expected behaviour associated with the relationship.
Source of Funds vs Source of Wealth
These two concepts are related but different.
Source of Funds
Source of funds refers to where the money involved in a particular transaction or account activity came from.
For example, funds may originate from:
- Salary
- Business receipts
- Sale of an asset
- Investment proceeds
- Financing
- Inheritance
- Other legitimate sources
Source of Wealth
Source of wealth concerns how a customer accumulated their overall wealth.
For example, wealth may have accumulated through:
- Long-term business ownership
- Employment
- Investments
- Property
- Inheritance
- Sale of a business
- Other legitimate economic activity
A customer may have substantial wealth while a particular transaction comes from a different identifiable source of funds.
Understanding both concepts can help institutions determine whether financial activity is consistent with the customer’s profile.
Beneficial Ownership
A major AML concern is understanding who ultimately owns or controls an account, company or legal arrangement.
The person appearing on an account or corporate document is not necessarily the person who ultimately benefits from or controls the funds.
Beneficial ownership controls therefore seek to establish the natural person or persons who ultimately own or control the relevant customer or arrangement, subject to the applicable legal and regulatory framework.
Complex ownership structures are not automatically suspicious. Businesses can have legitimate reasons for using holding companies, subsidiaries, partnerships and other structures.
The important question is whether the institution can understand the ownership and control structure and whether it has a reasonable commercial or economic explanation.
The FATF guidance on beneficial ownership and transparency emphasizes the importance of adequate, accurate and up-to-date beneficial ownership information.
Transaction Monitoring
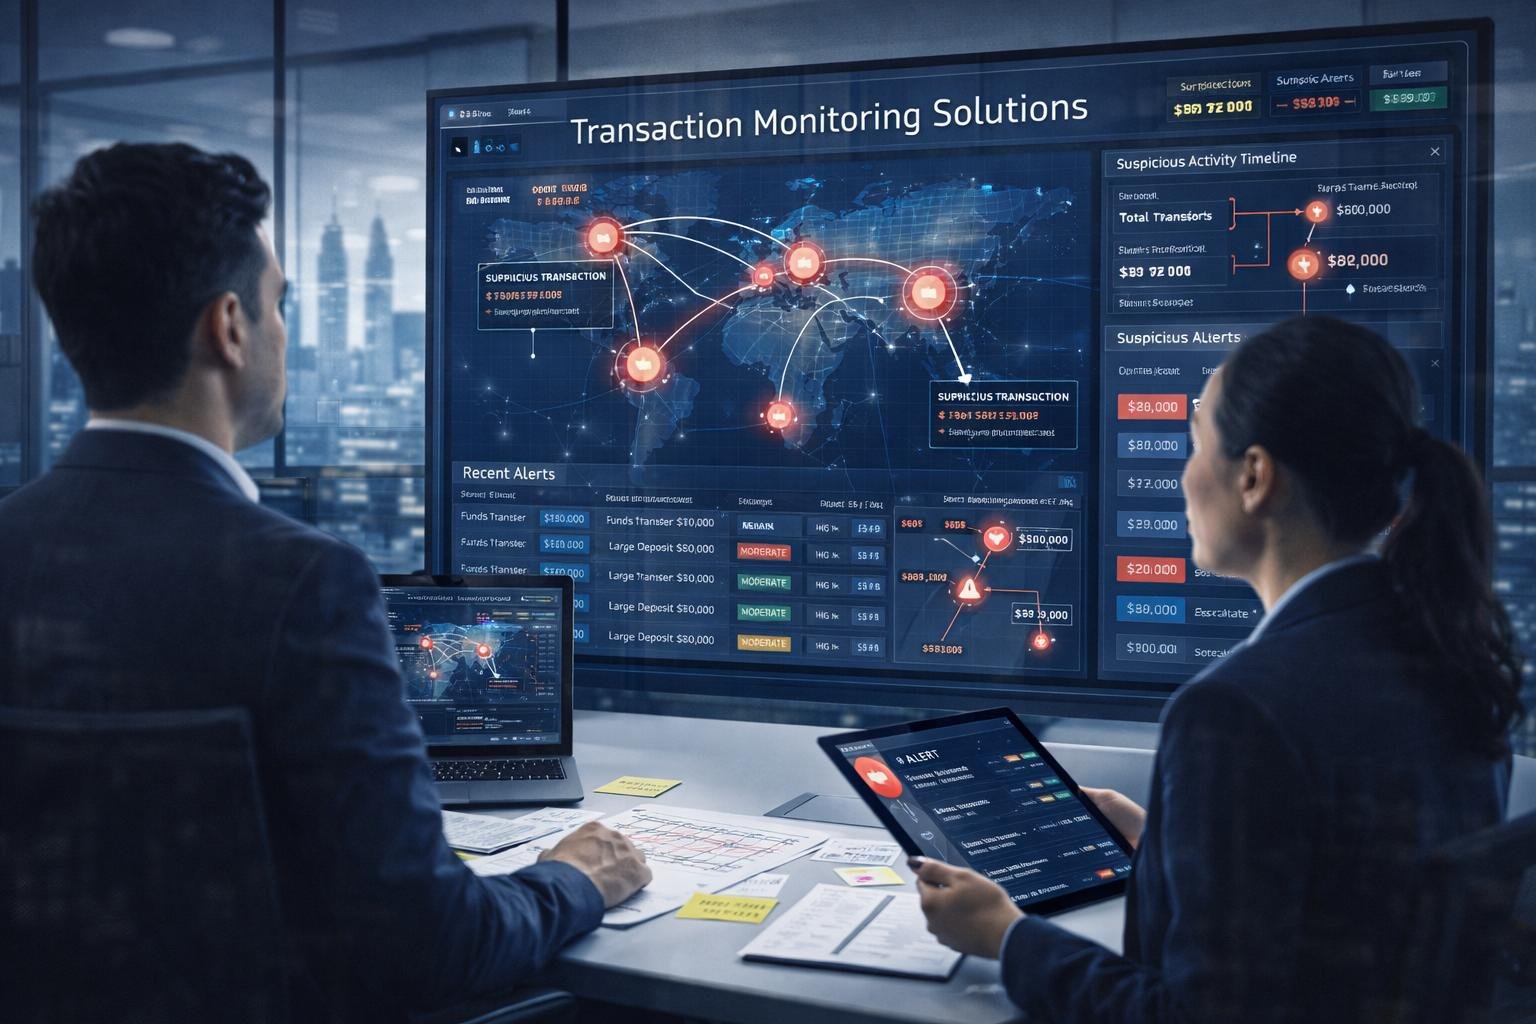
Effective anti money laundering programs rely on ongoing transaction monitoring to identify activity that may require further review.
Customer due diligence does not end after an account is opened.
Financial institutions should conduct ongoing monitoring appropriate to the customer’s risk profile.
Transaction monitoring may consider:
- Transaction frequency
- Transaction values
- Counterparties
- Geographic exposure
- Cash activity
- Transfers between related accounts
- Third-party activity
- Changes in account behaviour
- Transactions inconsistent with the customer’s profile
- Patterns involving multiple products or accounts
Effective monitoring is not simply about identifying large transactions.
A relatively small transaction can become significant when viewed together with other activity.
This is why transaction patterns and context are often more important than a single transaction viewed in isolation.
Common AML Red Flags for Bankers
The following indicators may warrant additional review depending on the circumstances:
Customer profile does not match account activity
A customer’s stated occupation, business or expected turnover may not appear consistent with actual transactions.
Unexplained third-party transactions
Funds may frequently move between the customer’s account and unrelated individuals or entities without an apparent economic explanation.
Rapid movement of funds
Funds may enter an account and leave shortly afterwards without a clear business or personal purpose.
Frequent transfers between related accounts
Multiple accounts belonging to related persons or entities may be used in ways that make the overall flow of funds difficult to understand.
Unusual cash activity
Cash deposits or withdrawals may be inconsistent with the customer’s stated business or normal account behaviour.
Sudden changes in transaction behaviour
A previously inactive account may suddenly begin receiving or transferring substantial amounts.
Unclear source of funds
The customer may be unable to reasonably explain where funds originated or provide information consistent with the transaction.
Complex ownership structures
Multiple companies, intermediaries or ownership layers may make it difficult to determine who ultimately controls or benefits from the relationship.
Transactions inconsistent with the stated business
A business account may show activity that does not reasonably correspond with its stated products, services or business model.
Unusual international activity
Cross-border transactions may require additional scrutiny where they are inconsistent with the customer’s business, profile or expected activity.
Use of an account by unexpected persons
Account activity may indicate that individuals other than the expected customer are effectively controlling or using the relationship.
Again, a red flag is not proof of money laundering.
It is an indicator that should be assessed in context.
Trade-Based Money Laundering
Trade-based money laundering (TBML) involves the misuse of legitimate trade transactions to move or disguise illicit value.
Trade activity can be complex because banks may have to assess information relating to:
- Customers
- Suppliers
- Buyers
- Goods or services
- Invoices
- Payments
- Shipping information
- Countries involved
- Transaction values
- Underlying business activity
Potential warning signs can include transactions that appear inconsistent with the customer’s established business, unusual pricing or volumes, unexplained counterparties, or transaction structures that lack an apparent commercial rationale.
For institutions operating in Pakistan, the State Bank of Pakistan’s framework for managing trade-based money laundering and terrorist financing provides an example of how trade-related customer due diligence and risk assessment can be incorporated into banking controls.
However, unusual trade activity should be assessed using available information rather than treated automatically as evidence of financial crime.
Correspondent Banking Risks
Correspondent banking allows financial institutions to provide services to other financial institutions, often across jurisdictions.
Because the relationship may involve customers and transactions that are not directly known to the correspondent institution, appropriate due diligence and risk assessment are important.
Relevant considerations can include:
- The respondent institution’s business
- Ownership and management
- AML/CFT controls
- Geographic exposure
- Products and services
- Customer base
- Transaction activity
- Regulatory environment
- Reputation and risk profile
The exact requirements depend on the applicable regulatory framework and risk assessment.
High-Risk Customers and Businesses
Some customers, products, services or relationships may present higher inherent financial crime risk.
Examples can include situations involving:
- Complex ownership
- High-value transactions
- Significant cash exposure
- Unusual cross-border activity
- Certain high-risk business models
- Politically exposed persons, where applicable
- Complex legal arrangements
- Higher-risk geographic exposure
- Transactions involving multiple intermediaries
Higher risk does not mean that the customer is involved in criminal activity.
It means that the institution may need enhanced due diligence, stronger monitoring or additional controls, depending on the circumstances and applicable requirements.
What Should a Banker Actually Look For?
A practical banker should continuously ask three questions:
1. Who is the customer?
Do we understand the customer’s identity, business, occupation, ownership and relationship with the bank?
2. What should reasonably be expected?
Does the customer’s transaction activity make sense based on what we know about the customer?
3. What has changed?
Has there been a significant change in transaction volume, counterparties, business activity, cash usage, geographic exposure or account behaviour?
These three questions can help turn AML from a document-checking exercise into a meaningful risk-management process.
Common Account and Transaction Patterns Requiring Review
Some transaction patterns deserve attention when they lack a reasonable explanation.
Examples include:
- Multiple accounts apparently controlled by connected persons
- Frequent transfers between related accounts without clear purpose
- Significant third-party transactions
- Repeated cash deposits followed by transfers
- Large transaction volumes inconsistent with the customer’s stated business
- Unexplained changes in account activity
- Funds moving through several accounts without an obvious commercial reason
- Transactions involving businesses that appear unrelated to the customer’s stated activities
- Accounts receiving funds from numerous unrelated parties
- Activity that appears inconsistent with the customer’s known financial capacity
The key principle is context.
A legitimate business can naturally have high transaction volumes, multiple counterparties and frequent transfers. AML analysis therefore requires an understanding of the customer’s actual business and circumstances.
Suspicious Transaction Reporting
Financial institutions may have obligations to report suspicious transactions or activity to the relevant financial intelligence or regulatory authority.
A suspicious transaction report does not necessarily mean that the customer has committed a crime.
It generally reflects the institution’s obligation to report activity that meets the applicable legal or regulatory threshold for suspicion.
The Financial Monitoring Unit (FMU) publishes reporting-related circulars and guidance in Pakistan, including current material relating to suspicious transaction reporting.
Institutions should therefore have clear internal procedures covering:
- Identification of potentially suspicious activity
- Escalation
- Investigation
- Documentation
- Decision-making
- Reporting
- Confidentiality
- Record retention
- Follow-up and monitoring
The Importance of Documentation
Good AML controls depend heavily on the quality of documentation.
Where a transaction or customer relationship is reviewed, the institution should be able to demonstrate:
- What was identified
- Why it was considered unusual
- What information was reviewed
- What explanation was obtained
- What additional checks were performed
- What conclusion was reached
- Who approved or reviewed the decision
- What further action was taken, where applicable
A strong audit trail helps demonstrate that AML controls are being applied consistently and thoughtfully.
Internal Controls and Governance
AML is not solely the responsibility of the compliance department.
Effective AML programs generally require cooperation among:
- Branch staff
- Relationship managers
- Operations teams
- Compliance
- Internal audit
- Risk management
- Senior management
- Information technology
- Legal functions
- Relevant control functions
The first line of defence often has important customer and transaction knowledge.
The second line typically provides risk management, compliance oversight and monitoring.
The third line, such as internal audit, provides independent assurance over the effectiveness of controls.
The exact governance structure varies by institution.
Training Is an Important AML Control
AML procedures are only effective if employees understand how to apply them.
Training should help staff understand:
- KYC requirements
- Customer risk
- Beneficial ownership
- Source of funds
- Source of wealth
- Transaction monitoring
- Red flags
- Escalation procedures
- Suspicious transaction reporting
- Record keeping
- Confidentiality requirements
Training should also use practical examples relevant to the institution’s products, customers and risk environment.
A Practical AML Checklist for Bankers
Before accepting or approving a customer relationship or transaction, consider the following:
Customer
- Do we know who the customer is?
- Has identity been appropriately verified?
- Do we understand the customer’s occupation or business?
Purpose
- Do we understand why the account or service is required?
- Is the expected activity reasonably clear?
Ownership
- Do we understand who owns or controls the customer?
- Have beneficial ownership requirements been addressed?
Financial Profile
- Does the expected transaction volume make sense?
- Is the source of funds reasonably understood?
- Where appropriate, is the source of wealth understood?
Transactions
- Are transactions consistent with the customer’s profile?
- Are there unexplained third-party transactions?
- Are there unusual cash or transfer patterns?
- Are there unexplained changes in behaviour?
Risk
- Are there factors requiring enhanced due diligence?
- Is ongoing monitoring appropriate to the identified risk?
Escalation
- Has unusual activity been properly documented?
- Has the matter been escalated according to internal procedures where required?
AML Is a Risk-Based Process
One of the most important concepts in modern AML compliance is the risk-based approach.
Not every customer presents the same level of risk.
A large established business with transparent ownership and predictable transactions may present a very different risk profile from a customer whose ownership is unclear and whose account activity is difficult to explain.
The objective is therefore not simply to create more paperwork.
The objective is to apply appropriate controls to the risks actually identified.
This requires judgement, reliable information, effective systems and properly trained staff.
The Role of Technology in AML
Modern financial institutions increasingly use technology to support AML controls.
Technology can assist with:
- Transaction monitoring
- Customer screening
- Pattern recognition
- Risk scoring
- Alert generation
- Network analysis
- Case management
- Data aggregation
- Reporting
However, technology does not eliminate the need for human judgement.
An automated alert may identify an unusual transaction, but an experienced analyst may need to determine whether the activity has a legitimate explanation.
The strongest AML environments therefore combine technology, data, controls and human judgement.
What Makes an AML Program Effective?
An effective AML framework should generally have:
- Clear policies and procedures
- Appropriate customer identification and due diligence
- Risk assessment
- Beneficial ownership controls
- Ongoing monitoring
- Effective suspicious activity escalation and reporting
- Employee training
- Strong management oversight
- Independent testing or audit
- Appropriate record keeping
- Effective systems and data
- Regular review as risks change
AML programs should evolve because financial crime risks evolve.
New payment methods, digital services, business models and technologies can create new risks that were not present when older controls were designed.
Ultimately, effective anti money laundering depends on combining customer knowledge, risk assessment, transaction monitoring, appropriate controls and sound professional judgement.
AML and the Wider Financial Crime Framework
Anti Money Laundering does not operate in isolation.
Financial institutions may also need controls relating to areas such as:
- Terrorist financing
- Proliferation financing
- Sanctions and targeted financial restrictions
- Fraud
- Corruption
- Bribery
- Tax-related risks
- Trade-based financial crime
- Cyber-enabled financial crime
The exact obligations depend on the institution, jurisdiction and applicable laws and regulations.
FATF and International AML Standards
The Financial Action Task Force (FATF) Recommendations provide an international framework addressing money laundering, terrorist financing and proliferation financing. The current Recommendations were amended in June 2026.
The FATF framework is designed to be implemented through national legal, regulatory and institutional systems. Countries therefore adapt international standards to their own legal and financial environments.
The risk-based approach is a central concept of the FATF framework.
For beneficial ownership specifically, the FATF’s guidance on transparency and beneficial ownership provides additional guidance for understanding ownership and control of legal persons and arrangements.
A Final Practical Perspective
AML compliance is sometimes viewed as a checklist exercise: collect identification documents, open the account, monitor transactions and file reports.
In practice, effective AML is much broader.
It is about developing a reasonable understanding of:
Who the customer is.
What the customer does.
Why the relationship exists.
Where the funds come from.
Who ultimately owns or controls the relationship.
What activity should reasonably be expected.
And whether actual activity makes sense in that context.
The most useful AML question is often not:
“Is this transaction large?”
It is:
“Does this activity make sense when considered in the context of what we know about the customer?”
That shift from transaction size to customer context is central to effective risk-based AML thinking.
Frequently Asked Questions
What does AML stand for?
AML stands for Anti-Money Laundering. It refers to the laws, regulations, policies, procedures and controls designed to prevent and detect the use of the financial system for money laundering and related financial crime.
What are the three stages of money laundering?
Money laundering is commonly described using three stages: placement, layering and integration. Real-world cases may not follow these stages in a fixed sequence.
What is KYC?
KYC means Know Your Customer. It involves obtaining and verifying appropriate customer information and understanding the nature and purpose of the relationship.
What is customer due diligence?
Customer Due Diligence, or CDD, involves identifying and verifying customers, understanding the purpose and nature of relationships, identifying beneficial owners where applicable, assessing risk and conducting appropriate ongoing monitoring.
What is beneficial ownership?
Beneficial ownership concerns the natural person or persons who ultimately own or control a customer, company or legal arrangement, subject to the applicable legal framework.
Is every unusual transaction suspicious?
No. An unusual transaction is an indicator that may require review. A legitimate explanation may exist.
What is a red flag in AML?
An AML red flag is an indicator of potentially unusual or higher-risk activity. A red flag does not by itself establish that money laundering has occurred.
What is transaction monitoring?
Transaction monitoring involves reviewing customer activity to identify transactions or patterns that may be inconsistent with the customer’s known profile, expected activity or identified risk.
Why is source of funds important?
Understanding source of funds helps an institution assess where money involved in a particular transaction originated and whether that source is reasonably consistent with available customer information.
Why is source of wealth different?
Source of wealth concerns how a customer accumulated their overall wealth, whereas source of funds concerns the origin of money involved in a particular transaction or relationship.
Related Financial Resources
Equicio also provides practical financial education and tools for understanding money and making informed financial decisions.
You can explore the Equicio Financial Tools & Calculators section for practical calculators.
For investment-related calculations, the Investment Return Calculator can help estimate profit or loss, total return and annualized return.
For understanding borrowing costs, the Loan EMI Calculator can help estimate monthly payments, total interest and total repayment.
The Compound Interest Calculator can also be used to explore how investments may grow over time when returns are reinvested.
Disclaimer
This article is provided for general educational and knowledge-sharing purposes only. AML requirements, reporting obligations, definitions and regulatory expectations vary between jurisdictions and may change over time.
Nothing in this article should be treated as legal, regulatory, compliance or professional advice. Financial institutions and professionals should always refer to the laws, regulations, regulatory instructions and official guidance applicable to their particular circumstances.
Where Pakistan-specific regulatory information is relevant, readers should consult the current instructions issued by the State Bank of Pakistan and the Financial Monitoring Unit, as applicable.
For current international AML standards, readers should consult the latest publications of the Financial Action Task Force (FATF).
1 thought on “Anti-Money Laundering (AML): A Practical Guide for Bankers”
Comments are closed.